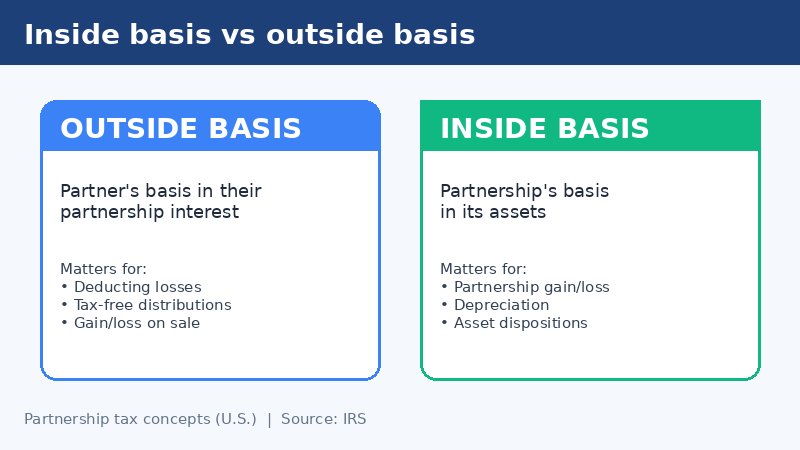
In U.S. partnership tax, outside basis is a partner’s basis in their partnership interest, while inside basis is the partnership’s basis in its assets. The IRS notes that these are separate concepts: outside basis tracks the partner’s investment in the interest, and inside basis tracks the partnership’s tax basis in the property it holds.
They often start equal after partners contribute cash or property, but can diverge after an interest is bought from another partner, after certain distributions, or when liabilities and special basis adjustments come into play. Outside basis matters because it helps determine whether a partner can deduct allocated losses, whether cash distributions are tax-free, and how much gain or loss arises when the interest is sold. Inside basis matters for partnership-level depreciation and for gain or loss when the partnership sells assets.
Source: IRS LB&I practice unit, “Partner’s Outside Basis” (revised Nov. 5, 2024); see also IRS Publication 541, Partnerships.